Summary
There are multiple ways to pay for independent living without selling your house, giving you flexibility to keep this important asset while enjoying a maintenance-free lifestyle. Explore rental income, home equity options, retirement funds, or a combination of strategies that align with your financial situation and long-term goals.
- Renting your home can generate monthly income to help offset independent living costs while retaining property ownership; consider hiring a property management company to handle tenant relations and maintenance
- Home equity options like HELOCs or reverse mortgages may provide financing, but eligibility requirements vary—consult a financial professional about how they affect your long-term plans
- Retirement income sources such as Social Security, pensions, investment distributions, and dividends can fund community living when combined strategically
- Many households combine multiple funding sources, such as using rental income for part of expenses while relying on retirement savings for the remainder
- Review what's included in independent living costs (housekeeping, utilities, dining, transportation, programs) and compare against your current household expenses to create a realistic budget
Moving to an independent living community does not necessarily mean selling your house. For many older adults, keeping a longtime home provides flexibility, preserves an important asset, or simply makes the transition feel more comfortable. Fortunately, there are several ways to pay for independent living without selling the house.
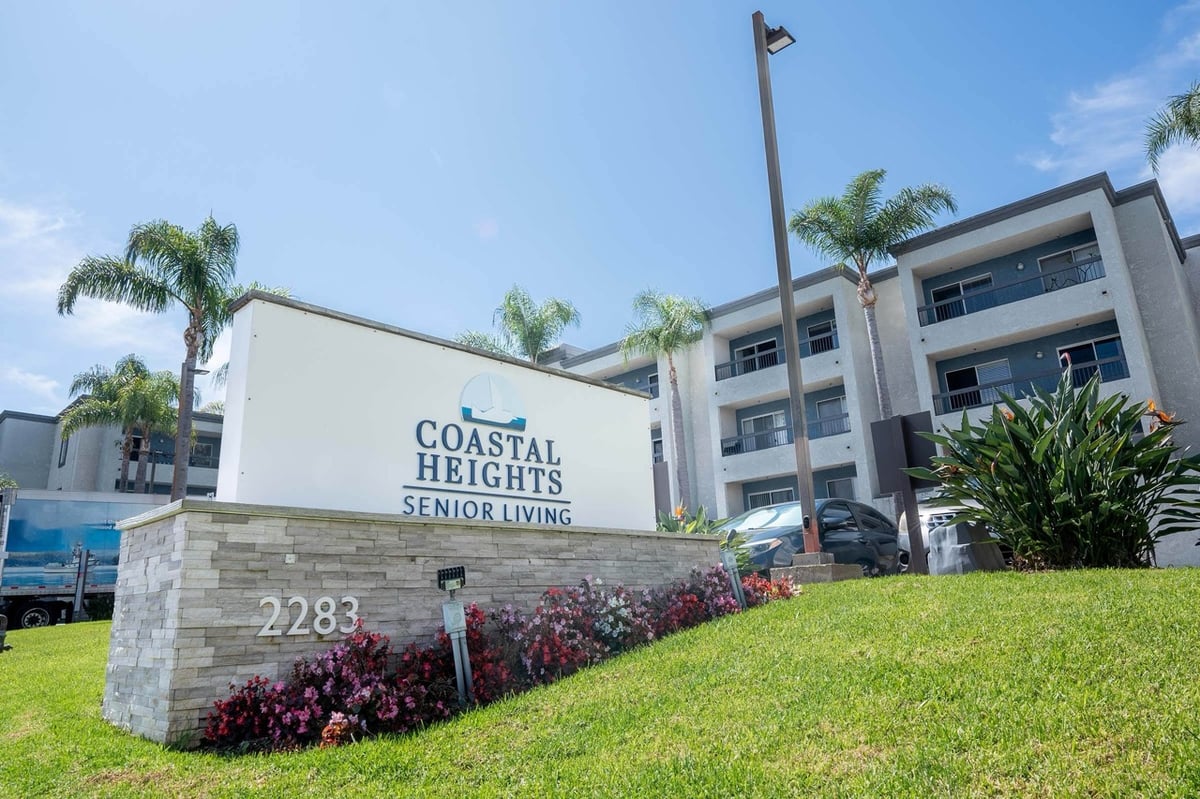
The right approach depends on your income, home equity, expenses, and long-term plans. Understanding the possibilities can help you decide whether you can afford senior living without a home sale while enjoying a simpler lifestyle at Coastal Heights.
Rent Your Home to Pay for Senior Living
One option is converting your house into a rental property. Depending on your local rental market, monthly income could offset some of the cost of independent living while allowing you to retain ownership of the property.
If managing tenants and maintenance does not fit the lifestyle you want, consider working with a property management company. A manager can handle rent collection, tenant communication, and property issues for a fee. This may make it more practical to rent your home to pay for senior living while living elsewhere.
Before becoming a landlord, factor in taxes, insurance, repairs, vacancies, management fees, and other expenses. Comparing expected net rental income with your independent living costs can give you a more realistic picture.
Consider Whether Home Equity Can Help
Home equity may offer additional financial flexibility, but the available options depend on how the property will be used after you move.
For example, a home equity line of credit (HELOC) may allow qualified homeowners to borrow against available equity. If you are considering a reverse mortgage, eligibility and occupancy requirements are especially important. Because these products generally require the property to remain your principal residence, permanently moving to an independent living community can affect eligibility or repayment.
Before using home equity for financing independent living while keeping your home, speak with a qualified financial professional or lender about the requirements, costs, and potential impact on your long-term plans.
Use Retirement and Investment Income
Some older adults can fund independent living through a combination of existing income sources without selling their property. Depending on your financial situation, those resources may include:
- Social Security or pension income
- Retirement account distributions
- Investment or dividend income
A financial advisor can help you determine a sustainable withdrawal strategy and understand potential tax implications.
It's also helpful to compare your current household spending with what's included at Coastal Heights. Here, Independent Living offers housekeeping, apartment maintenance, utilities excluding phone service, basic cable and internet, and complimentary scheduled transportation.
Residents also have access to Elevate® Dining, Vibrant Life® programs, and Health & Fitness amenities. Consolidating some everyday expenses into a recurring community cost may make budgeting simpler.
Explore Short-Term Financing Options
If you want to keep your house while living in a community, short-term financing may also be worth discussing with a financial professional. A HELOC, for example, can provide access to available home equity without requiring an immediate sale.
Bridge financing may be another possibility for homeowners who expect to sell later but need funds during the transition. Loan availability, repayment terms, interest rates, and eligibility vary, so these options should be evaluated carefully rather than viewed as a one-size-fits-all solution.
Consider comparing:
- Upfront and ongoing borrowing costs
- Expected rental or retirement income
- Current home expenses and Independent Living costs
Looking at the full financial picture can help you determine whether keeping your property supports your broader goals.
Combine Financial Strategies for Greater Flexibility
For some households, the answer is not a single funding source. Financial options for independent living without selling can be combined based on your circumstances. You might use rental income for part of your monthly expenses while relying on retirement income for the remainder. Another household may use savings during the initial transition and decide what to do with the property later.
This flexibility can be particularly valuable if you are not ready to make a permanent decision about your house. Keeping the property for a period of time may give you an opportunity to settle into community life before determining what makes the most financial sense.
At Coastal Heights, the move to Independent Living is also about simplifying everyday routines. Associates handle housekeeping and maintenance, while scheduled transportation, restaurant-style Elevate® Dining, Vibrant Life® programs, and inviting community spaces provide more ways to spend your time on the people and experiences you enjoy.
Plan Your Move With the Full Financial Picture in Mind
There's no single best way to pay for independent living without selling your home. Rental income, retirement funds, investments, and home-equity options can each play a role depending on your finances and future plans.
Before making a decision, consider meeting with a financial or tax professional who can review your specific circumstances. With a thoughtful plan, it may be possible to preserve your home while enjoying the convenience, connection, and maintenance-free lifestyle of Independent Living at Coastal Heights.
Schedule a tour of Coastal Heights to explore the apartment homes, amenities, programs, and lifestyle that could make your next chapter simpler.